A yearly eye exam can feel like basic preventive care, especially as you approach retirement. But the answer to “Does Medicare cover vision exams?” depends on why you need the exam. Original Medicare generally does not pay for routine eye exams or glasses, but it can cover certain medically necessary eye care.
That difference matters when you are choosing Medicare coverage at age 65. A plan that handles hospital and doctor visits well may still leave you paying out of pocket for the routine vision services you expect to use every year.
Does Medicare Cover Vision Exams Under Original Medicare?
Original Medicare includes Part A for hospital care and Part B for outpatient and doctor services. Medicare Part B may cover eye exams, tests, and treatment when they are needed to diagnose, monitor, or treat a medical eye condition.
It does not usually cover a standard vision exam to check whether you need new glasses or contacts. It also generally does not cover the cost of eyeglasses, contact lenses, or refraction testing, which is the portion of an exam that measures your prescription.
In practical terms, a visit prompted by blurry vision, an eye disease, diabetes, or a suspected medical problem may qualify for Medicare coverage. A visit scheduled simply because it has been a year since your last exam likely will not be covered by Original Medicare.
Even when Medicare covers the service, you may still owe your Part B deductible and coinsurance. If you have a Medicare Supplement plan, it may help pay some of those Medicare-approved out-of-pocket costs. A supplement does not usually add coverage for routine eye exams or eyewear.
When Medicare May Pay for Eye Care
Medicare Part B covers several important vision-related services in specific situations. Coverage is tied to medical need and Medicare rules, not just to the fact that the service involves your eyes.
Diabetic eye disease screenings
If you have diabetes, Medicare Part B generally covers an eye exam once each year to check for diabetic retinopathy. The exam must be performed by an eye doctor who is legally allowed to provide the service in your state.
This benefit is especially valuable because diabetic eye disease can develop before you notice major changes in your sight. Ask the provider’s office whether the visit is being billed as a Medicare-covered diabetic eye exam rather than as a routine vision exam.
Glaucoma tests for higher-risk individuals
Medicare may cover glaucoma testing once every 12 months for people considered at high risk. This can include people with diabetes, people with a family history of glaucoma, Black Americans age 50 or older, and Hispanic Americans age 65 or older.
The test must be performed or supervised by an eye doctor who is qualified under state law. Your share of the cost depends on whether the provider accepts Medicare assignment and whether you have other coverage that helps with Part B cost sharing.
Cataract surgery and certain lenses
If cataracts interfere with your vision and cataract surgery is medically necessary, Medicare Part B generally helps cover the surgery. It also typically covers one pair of standard eyeglasses or one set of contact lenses after cataract surgery that includes implantation of an intraocular lens.
This is a narrow benefit. Medicare does not usually pay for upgraded frames, premium lens options, or other extras beyond the covered standard option. Before surgery, ask for a written estimate that separates Medicare-covered charges from elective upgrades.
Tests and treatment for diagnosed eye conditions
Original Medicare can cover medically necessary services for conditions such as age-related macular degeneration, retinal problems, eye injuries, infections, and other diagnosed diseases. That may include specialist visits, imaging, injections, medications administered in a clinical setting, or surgery when Medicare coverage requirements are met.
The key question is whether the service is medically necessary to evaluate or treat a condition. Your eye doctor can explain the reason for the test, but it is still wise to confirm expected costs before the appointment.
What Original Medicare Usually Does Not Cover
Many people are surprised by how much routine vision care remains their responsibility under Original Medicare. In most cases, you pay the full cost for a standard annual vision exam, eyeglass prescriptions, frames, lenses, contact lenses, and routine fitting services.
Medicare’s Annual Wellness Visit does not replace a comprehensive eye exam, either. That visit focuses on a personalized prevention plan and general health risks. It is not a routine vision benefit.
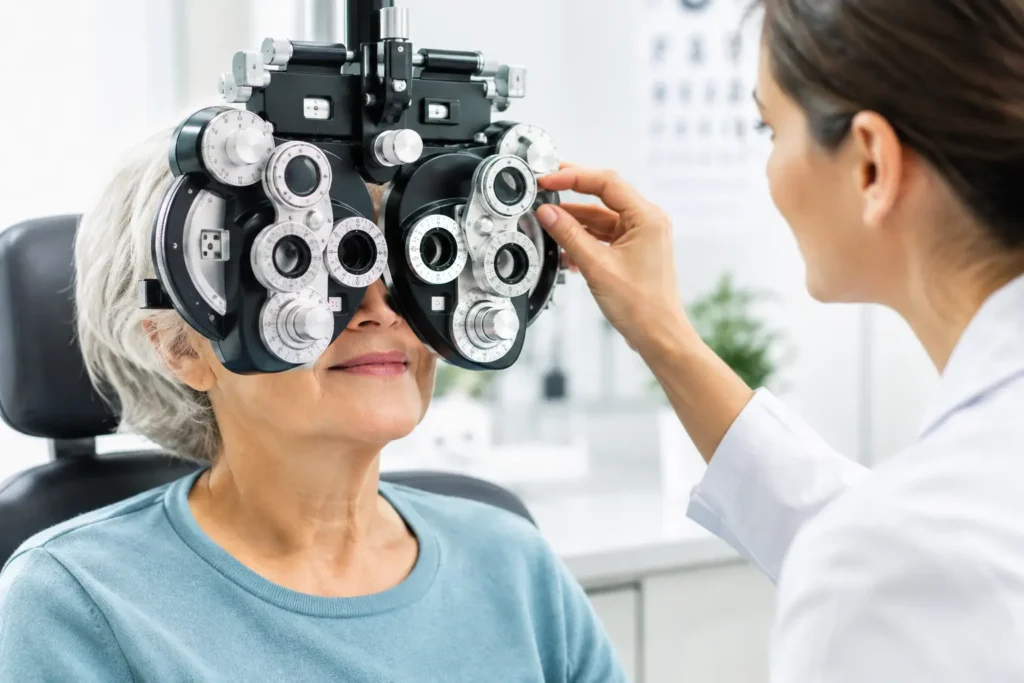
There can also be a mixed bill during one eye appointment. For example, an ophthalmologist may perform a Medicare-covered medical evaluation for an eye condition while the refraction portion remains your responsibility. Ask the office ahead of time which parts of the visit Medicare will and will not cover.
Can Medicare Advantage Cover Routine Vision Exams?
Medicare Advantage plans, also called Part C plans, must cover everything Original Medicare covers except hospice care, which remains covered by Original Medicare. Many Medicare Advantage plans also offer extra benefits, and routine vision care is one of the more common additions.
Depending on the plan available in your area, vision benefits may include a routine eye exam, an allowance for frames or lenses, contact lens coverage, or discounts through a participating vision network. These benefits can make budgeting easier if you regularly wear glasses or want an annual exam.
But the details matter. One plan may cover a routine exam with a small copay but provide a limited eyewear allowance. Another may offer a larger allowance but require you to use in-network providers. Some benefits are available only once per calendar year, while others follow a different benefit period.
Before choosing a Medicare Advantage plan because of its vision benefit, check the plan’s provider network, annual allowance, copays, prior authorization rules, and the types of lenses or eyewear included. Also consider the full plan picture: your doctors, prescription drugs, hospitals, monthly premium, and maximum out-of-pocket limit matter just as much as vision coverage.
What About Medicare Supplement Plans and Stand-Alone Vision Plans?
A Medicare Supplement insurance plan, often called Medigap, works alongside Original Medicare. It can help with certain deductibles, copayments, and coinsurance for Medicare-approved services. It generally does not pay for routine eye exams, glasses, or contact lenses because Original Medicare does not cover those services.
Some people with Original Medicare choose to pay for routine vision care out of pocket. Others consider a separate dental and vision policy. These plans are not all alike. A low premium may come with waiting periods, provider restrictions, limited allowances, or benefits that do not match the eyewear you prefer.
The right choice depends on how often you use vision services and how predictable you want your costs to be. If you only need an occasional exam, paying directly may be reasonable. If you buy new glasses regularly or want broader routine coverage, comparing Medicare Advantage options and separate vision plans may be worthwhile.
Questions to Ask Before You Enroll
As you near 65, vision benefits should be part of your Medicare comparison, not an afterthought. A few clear questions can help prevent surprises after enrollment:
- Is a routine annual eye exam covered, and what is the copay?
- Does the plan include an allowance for frames, lenses, or contacts?
- Which optometrists and ophthalmologists are in the plan’s network?
- Does the benefit cover progressive lenses, bifocals, or lens upgrades?
- How are medically necessary eye treatments covered under the plan?
If you have diabetes, glaucoma risk, cataracts, macular degeneration, or another ongoing eye condition, bring that information into the conversation. Your medical eye care needs may be more important than a routine eyewear allowance.
Choosing Medicare is not just about what is covered on paper. It is about knowing where you may face out-of-pocket costs and selecting coverage that fits your doctors, prescriptions, budget, and everyday health needs. Before your Initial Enrollment Period ends, take time to compare your options and get guidance from a licensed Medicare professional who can help you understand the vision benefits available where you live.