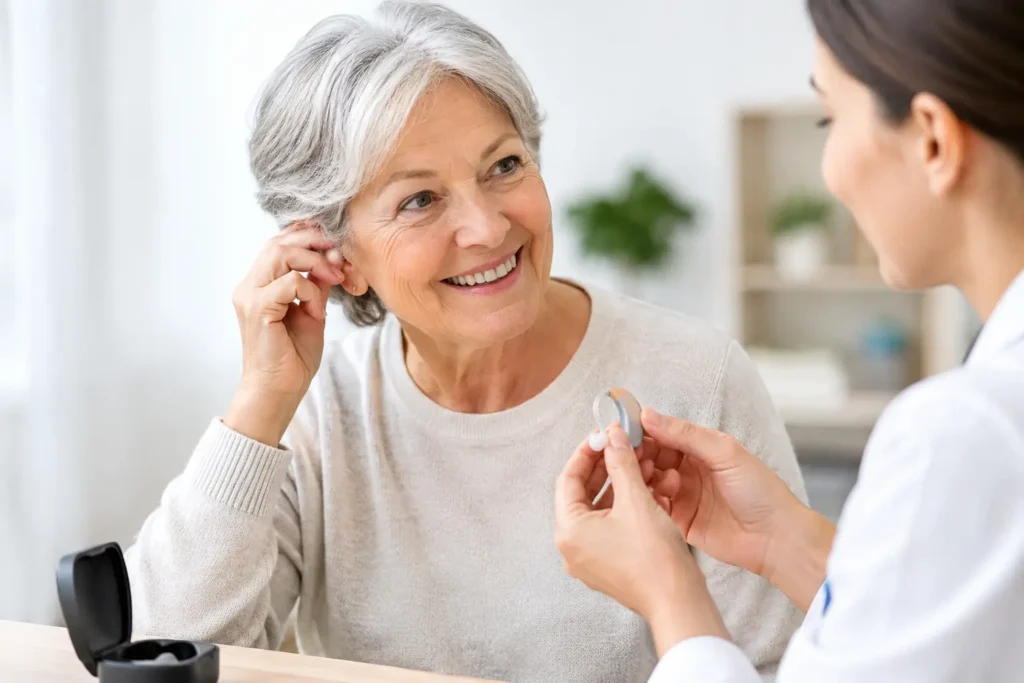
Hearing changes can be gradual, but the cost of addressing them can feel immediate. So, does Medicare cover hearing aids? For most people with Original Medicare, the straightforward answer is no. Original Medicare generally does not pay for hearing aids or the routine exams used to fit them. However, your Medicare choices can make a meaningful difference in what you pay for hearing care.
If you are turning 65, this is one of the benefits worth asking about before you enroll. Hearing coverage is not standardized across all Medicare plans, and a lower monthly premium does not always mean a lower total cost when you need services that Medicare leaves out.
What Original Medicare Does and Does Not Cover
Original Medicare includes Part A, which primarily covers inpatient hospital care, and Part B, which covers outpatient medical services. Neither Part A nor Part B generally covers hearing aids, batteries, or routine hearing exams for the purpose of prescribing and fitting hearing aids.
That means you may be responsible for the full cost of a hearing evaluation performed solely to select a hearing aid, the device itself, fittings, adjustments, and replacement batteries or accessories. Those expenses can add up quickly, especially if you need devices for both ears.
There is an important distinction to understand: Medicare Part B may cover certain diagnostic hearing and balance exams when they are medically necessary and ordered by a doctor or other qualified provider. For example, if you develop sudden hearing loss, dizziness, ringing in the ears, or another symptom that needs medical evaluation, Part B may help cover the diagnostic testing.
Coverage for a diagnostic exam does not mean Medicare will cover a hearing aid afterward. The exam may be covered under Part B rules, while the hearing aid remains an out-of-pocket expense.
Does Medicare Cover Hearing Aids Through Medicare Advantage?
Medicare Advantage plans, also called Part C plans, are offered by private insurance companies approved by Medicare. They must cover all Medicare-covered Part A and Part B services, except hospice care, which remains covered by Original Medicare. Many plans also include additional benefits that Original Medicare does not provide, and hearing benefits are a common example.
Some Medicare Advantage plans may offer a routine hearing exam, an allowance toward hearing aids, or access to hearing aid providers within a plan network. But benefits vary widely by plan and by county. One plan may provide a set dollar allowance every year or every few years, while another may cover only specific hearing aid models or require you to use a contracted provider.
Before choosing a plan based on hearing benefits, look past the headline amount. Ask how the benefit actually works. A plan with a $1,000 hearing aid allowance may still leave you with substantial costs if the devices you need are priced above that amount. You will also want to know whether the allowance applies per ear or per person, whether an annual hearing exam is included, and whether prior authorization is required.
A plan’s provider network matters, too. If you already see an audiologist or hearing specialist you trust, confirm whether that provider participates before enrolling. Changing plans later may be possible, but it is much easier to check these details during your initial enrollment decision.
Medicare Supplement Plans Usually Do Not Add Hearing Benefits
A Medicare Supplement insurance plan, often called Medigap, works alongside Original Medicare. It can help pay certain deductibles, copayments, and coinsurance for Medicare-approved services. But it does not typically add coverage for services that Original Medicare excludes.
Because Original Medicare does not generally cover hearing aids or routine hearing aid fittings, a Medicare Supplement plan generally will not pay for them either. This is a point that surprises many people comparing Medicare options for the first time.
Medigap can still be a strong fit for someone who wants broad access to doctors and more predictable costs for Medicare-covered medical care. But if hearing, dental, vision, fitness, or other extra benefits are a high priority, it is worth comparing Medicare Advantage plans carefully rather than assuming a supplement will include those services.
What About Over-the-Counter Hearing Aids?
Over-the-counter hearing aids are available without a prescription for adults with perceived mild to moderate hearing loss. They may cost less than prescription devices purchased through an audiologist, but Original Medicare generally does not cover them.
Medicare Advantage coverage for over-the-counter hearing aids depends on the individual plan. Some plans may include an allowance that can be used through a designated catalog or participating vendor. Others may limit coverage to prescription hearing aids obtained through specific providers.
Lower price does not always mean the same level of service. Prescription hearing aids may come with professional testing, fitting, follow-up adjustments, and support for more complex hearing needs. Over-the-counter devices can be a reasonable option for some people, but they are not a substitute for medical care if you have sudden hearing loss, pain, drainage, dizziness, hearing loss in one ear, or a rapidly worsening problem.
Questions to Ask When Comparing Medicare Plans
Hearing coverage should be evaluated alongside your doctors, prescriptions, preferred hospitals, monthly premium, and maximum out-of-pocket costs. A plan that looks attractive because it includes hearing benefits may not be the right fit if it does not cover your medications well or requires you to leave your preferred provider network.
As you compare options, get clear answers about the hearing benefit: Does the plan cover a routine hearing exam? What is the maximum amount available for hearing aids? Is the amount available every year, every two years, or on another schedule? Which audiologists, hearing centers, and device brands are included? Will you pay a copay, coinsurance, or the difference above the plan allowance?
Also ask whether the benefit has changed for the plan year you are considering. Medicare Advantage benefits, provider networks, premiums, and formularies can change from year to year. A benefit you saw in an advertisement or had under a previous plan may not apply to the plan you are evaluating now.
Timing Matters When You Are Turning 65
Your Initial Enrollment Period is a key opportunity to review Medicare coverage choices. For most people, this window begins three months before the month they turn 65, includes their birthday month, and continues for three months afterward. Waiting until you need a hearing aid to think about coverage can limit your choices and create unnecessary out-of-pocket costs.
If you are delaying Medicare because you have qualifying employer coverage, your timing may work differently. The details depend on the size of the employer and the type of coverage you have, so it is wise to confirm your enrollment path before making changes to your health insurance.
A licensed Medicare professional can help you compare plan options available where you live and explain how hearing benefits fit into the bigger picture. The goal is not simply to find a plan that mentions hearing aids. It is to choose coverage that supports your expected healthcare needs, your budget, and the doctors and services you are most likely to use.
Hearing care may be only one piece of your Medicare decision, but it is a practical one to address early. Taking the time to compare the actual benefit details before you enroll can help you move into Medicare with fewer surprises and greater confidence.